Canada's Proposed Productivity Mega Deduction: What Equipment Buyers Should Know
November 4, 2026
Canadian businesses considering investments in machinery and equipment may have a new tax-planning opportunity. The federal government's proposed Productivity Mega Deduction could allow eligible businesses to deduct up to 100% of the cost of qualifying equipment in the year it becomes available for use.
Announced on September 15, 2026, the proposed measure is designed to encourage business investment by accelerating tax deductions for a broader range of capital assets.
What Is the Productivity Mega Deduction?
Under Canada's traditional Capital Cost Allowance (CCA) system, businesses generally deduct the cost of depreciable machinery and equipment over several years.
The proposed Productivity Mega Deduction would allow qualifying businesses to deduct the full cost of eligible equipment in the year it becomes available for use, potentially reducing taxable income sooner.
This is a tax deduction, not a government rebate or cash incentive. The actual financial benefit depends on each business's circumstances.
What Types of Equipment May Qualify?
The proposed measure covers a broad range of depreciable business assets. Depending on their classification and use, eligible machinery could potentially include:
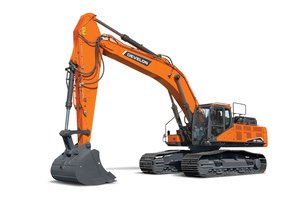
- Excavators and mini excavators
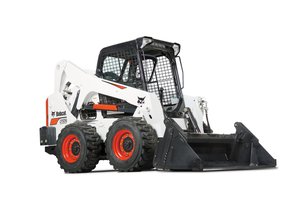
- Compact track loaders and skid-steer loaders
- Wheel loaders and other construction machinery
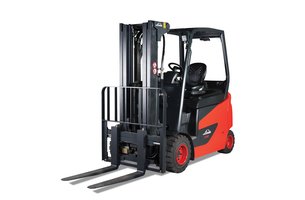
- Forklifts and material handling equipment
- Telehandlers and other specialized equipment
- Qualifying attachments and related capital equipment
Not all equipment purchases will qualify automatically. Eligibility depends on the applicable CCA classification, transaction details, business use and other tax requirements.
Can Used Equipment Qualify?
Yes. Qualifying used equipment may also be eligible.
Previously used machinery may qualify if purchased in an arm's-length transaction, provided neither the buyer nor a non-arm's-length party has previously owned the equipment. Purchases involving tax-deferred rollovers may also be excluded, and other eligibility conditions apply.
For businesses considering pre-owned construction or material handling equipment, this could provide an additional factor to consider when planning capital purchases.
When Would the Deduction Apply?
The proposed rules generally apply to eligible equipment acquired on or after September 15, 2026.
The deduction would be available in the taxation year the equipment becomes available for use, subject to the applicable tax rules.
Businesses considering year-end purchases should discuss acquisition timing, equipment delivery and availability for use with their tax advisor.
What About Financing or Leasing?
Businesses purchasing machinery through financing may still be eligible for capital cost allowance deductions, depending on the ownership structure and financing agreement.
Leasing arrangements can be treated differently. Businesses should confirm whether their agreement permits them to claim CCA before assuming the proposed deduction will apply.
What Should Equipment Buyers Do Next?
If your business is planning to purchase machinery, this may be an opportunity to review your equipment investment strategy.
Consider your operational requirements, planned equipment purchases and the potential tax implications with your accountant or financial advisor.
Our equipment specialists can help you explore new and used machinery options suited to your operation.
Learn More
For additional information about the proposed Productivity Mega Deduction, including eligibility requirements and restrictions, visit the Department of Finance Canada's official announcement.
Important Notice: The Productivity Mega Deduction is a proposed federal tax measure and remains subject to legislative approval and final implementation rules. This article is provided for general information only and does not constitute tax, accounting, legal or financial advice. Equipment eligibility and tax treatment must be confirmed with a qualified tax professional.